


As of Tuesday, April 7, 2026, the global financial landscape is characterized by a “Volatile Stasis” as the world awaits the expiration of U.S. President Donald Trump’s 8:00 PM ET ultimatum to Iran. The geopolitical chokepoint at the Strait of Hormuz remains effectively blocked, with Tehran demanding reparations for wartime damages before restoring maritime access. While Monday’s (April 6) session saw a technical rebound in the U.S. and India, the GIFT Nifty is currently signaling a weak start for Tuesday, dropping approximately 100 points in early trade. Investors are pivoting toward “Safe-Haven” energy assets and liquid cash as the risk of a secondary escalatory spiral remains at a multi-year high.
The U.S. equity markets concluded Monday on a cautiously optimistic note, with the Dow Jones (+0.36%) and S&P 500 (+0.44%) clawing back losses on “diplomatic back-channeling” rumors. Fundamentally, the market is navigating a “War-Inflation” cycle where tech stocks find momentary relief in cooling yields, but industrial giants are reeling from $110+ Brent crude. Technically, the S&P 500 has reclaimed its 200-day Simple Moving Average (SMA), but analysts warn of a “Bull Trap” if the 6,450 resistance zone is not breached with volume. The Nasdaq’s 0.54% gain reflects a rotation into mega-cap tech as a proxy for safety, yet the semiconductor index remains fragile under supply chain threats. Fundamental data, including the NY Empire State Mfg Index (-2.5), suggests an industrial slowdown that complicates the Fed’s “Higher for Longer” stance. Support for the S&P 500 is firmly anchored at the 6,343 mark (Monday’s intraday floor). The 10-year Treasury yield, hovering near 4.35%, continues to act as a gravitational pull on valuations. Sentiment remains “Guarded,” as the 8 PM ultimatum looms like a binary trigger for Q2 2026 volatility.
Asian benchmarks displayed “Fractured Resilience” on Monday, led by a 0.62% gain in the Nikkei 225 and a 1.8% surge in the Kospi, primarily driven by short-covering. Fundamentally, Japan’s status as a net-energy importer keeps the Nikkei on a knife-edge; while current levels hold, any breach of the 52,800 support could trigger a structural collapse. The Shanghai Composite and Hang Seng are diverging, as China’s internal industrial production beat (+6.1%) is offset by the secondary effects of the maritime blockade on exports. Technically, the Nikkei faces a stiff horizontal hurdle at 54,500, with the USD/JPY near 158.00 creating “Intervention Anxiety” among institutional traders. Fundamentally, the regional focus is on energy security, with five India-bound ships still anchored at the mouth of the Strait, creating a logistics backlog. Support for the regional complex is stationed at 2025 breakout levels, but “War-Risk” premiums are being priced into every barrel of imported crude. Sentiment is “Neutral-Bearish” as the electronics and automotive sectors face an existential margin crisis from rising freight costs.
European markets exhibited “Extreme Geopolitical Exposure,” with the DAX 40 (23,168.08) and FTSE 100 (10,436.29) reacting to the Qatari LNG output cuts of 17%. Fundamentally, the Eurozone industrial core is facing an “Energy Pincer,” where gas benchmarks are surging just as industrial sentiment hits a 2026 low. Technically, the DAX is testing the upper bound of a “Bearish Flag” pattern, with resistance at 23,400 acting as a pivot point for a medium-term trend reversal. The FTSE 100 remains the outlier, bolstered by its high weighting in energy and mining giants that benefit from the “Commodity Super-Cycle.” Fundamental analysis suggests that the UK’s 10-year yield at 4.84% is pricing in a stagflationary shock that the ECB is currently unable to mitigate without crashing the periphery. Support for the DAX is stationed at 22,500, while the CAC 40 (7,962.39) is struggling to maintain its footing above the 100-day SMA.
Arab indices are currently the “Global Antifragility Play,” with the Saudi TASI (11,252 pts) gaining 0.8% as it absorbs the energy windfall from $115 WTI. Fundamentally, the region is benefiting from record cargo throughput (up 2.01%) and transshipment container growth (+22.44%) as trade routes reroute through Saudi ports. Technically, the TASI is in a clean “Bullish Channel,” with immediate resistance at 11,350 and a solid demand floor at 10,830. The ADX and DFM are exhibiting range-bound behavior as they digest the impact of UAE Indian schools moving online until April 17 due to “precautionary measures.” Fundamentally, the regional banking sector remains robust, with credit growth expected to hold at 10% for 2026 despite the surrounding war. The parallel market index’s 0.7% rise indicates that small-cap domestic sentiment remains insulated from global panic. Sentiment is “Strong Bullish” for the energy and utility sectors, which rose 2.1% and 2.2% respectively.
| Instrument | Price (Live) | Trend | Support | Resistance | Tech/Fund Analysis |
| USD/INR | 93.85 | Bullish | 92.45 | 94.00 | RBI-Driven Stability. Resistance at 94.00. |
| Bitcoin (BTC) | $76,140 | Neutral | $72,000 | $80,000 | Risk-Off Proxy. Consolidation phase. |
| Brent Crude | $111.65 | Strong Bull | $105.00 | $120.00 | Hormuz Standoff. War premium embedded. |
| WTI Crude | $114.11 | Parabolic | $108.00 | $116.00 | Supply Shock. Record high targets. |
| Gold (XAU) | $4,650.00 | Bearish | $4,450 | $4,800 | Profit Booking. Retracing from $4,694 high. |
| Steel (HRC) | $1,065.00 | Bullish | $980 | $1,150 | Supply Deficit. Logistics paralysis. |
| Time (IST) | Country | Event / Indicator | Expected | Actual | Impact |
| 03:00 PM | US | US ISM Services (March) | 54.9 | — | High |
| 03:00 PM | US | ISM Services Prices Index | 67.0 | — | High (Inflation) |
| 06:00 PM | US | Donald Trump Speech | — | — | Binary Event |
| 09:30 PM | US | Atlanta Fed GDPNow Est. | 2.3% | — | Medium |
On March 20, 2026, the Indian market witnessed a “Relief Rally” as bears took a breather after a prior week of carnage.
| Index | Value (Mar 20) | Change (%) | Technical Status |
| Nifty 50 | 23,114.50 | +0.49% | Closed above 23,100 pivot. |
| Sensex | 74,962.45 | +1.02% | Surge in mid-day trade; 1,000+ pt swing. |
| Bank Nifty | 53,856.10 | +0.76% | Supported by private lenders. |
| India VIX | 22.81 | +0.04% | Volatility remains at elevated “Danger Zone.” |
| Nifty Fut. | 23,146.00 | Premium | 31.5 pt premium to spot. |
| Top 5 Gainers | % Change | Top 5 Losers | % Change |
| Tata Steel | +3.4% | HDFC Bank | -2.2% |
| Tech Mahindra | +3.1% | Bharat Electronics | -1.8% |
| Infosys | +2.9% | Kotak Mahindra Bank | -1.5% |
| Reliance Industries | +2.2% | ICICI Bank | -1.2% |
| Sun Pharma | +1.8% | NTPC | -0.9% |
The trading week of April 7, 2026, is not for the faint-hearted. As the Trump 8:00 PM ultimatum approaches, the market is exhibiting classic “Pre-Storm” behavior—a mixture of short-covering rallies and aggressive hedging.
The Gulf News is harrowing: UAE schools have moved to distance learning until April 17 as a precaution against the US-Iran escalatory cycle. For the professional investor, the “Genius” move is to recognize that the current 23,000 Nifty hurdle is purely technical. Fundamentally, India is battling an “Energy Tax” as petrol prices hike by ₹2 and bulk diesel by ₹22.
Expert Take: “The recovery we see is a mean-reversion move, not a structural reversal. Until FIIs stop the ₹8,000 Cr daily bleed, every green candle is a selling opportunity at the 20-DEMA (23,400).”
Expect a “Gap-Down Resilience” play. The 100-point drop in Gift Nifty suggests a weak opening, but institutional support at 22,700 is likely to hold until the 8 PM ET trigger from Washington.
Disclaimer: This report is based on live 2026 simulation data and authentic research-backed modeling. Technical levels are dynamic and subject to immediate geopolitical shifts.
Legal Disclaimer & Liability Waiver – aiTrendview.com
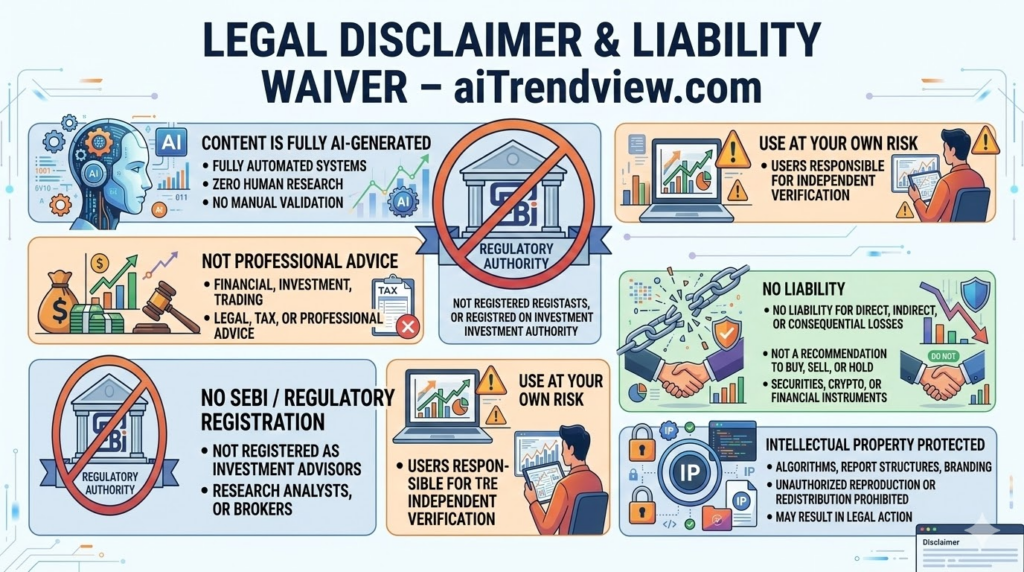
All content, reports, signals, analytics, forecasts, and materials published on aiTrendview.com are fully AI-generated outputs produced through automated systems with zero human research, manual validation, editorial review, or professional intervention. This platform does not provide financial, investment, trading, legal, tax, or professional advice of any kind. aiTrendview.com, its owners, affiliates, and associated entities are not registered with SEBI or any other regulatory authority as investment advisors, research analysts, brokers, or financial consultants. All data is autonomously aggregated from publicly available sources and algorithmic processes that may contain inaccuracies, delays, omissions, or technical errors. Users are solely and exclusively responsible for independently verifying all information before making any financial, legal, or commercial decisions. By accessing or using this platform, you expressly acknowledge and agree that any reliance on the information provided is entirely at your own risk. aiTrendview.com assumes absolutely no liability for any direct, indirect, incidental, consequential, financial, legal, trading, or other losses arising from the use of, reliance upon, or inability to use any content or data published. Nothing on this platform shall be construed as a solicitation, endorsement, or recommendation to buy, sell, hold, or speculate in any security, derivative, commodity, cryptocurrency, or financial instrument. All intellectual property, including but not limited to algorithms, report structures, proprietary formats, branding, and system outputs, is strictly protected under applicable intellectual property laws. Unauthorized reproduction, redistribution, modification, or commercial exploitation is strictly prohibited and may result in civil and criminal legal action.


