


Date: Monday, April 6, 2026 | Strategic Outlook: Extreme Volatility / Geopolitical Churn
As of Monday, April 6, 2026, global financial markets are undergoing a violent “re-rating” following the Good Friday long weekend. The primary catalyst is the expiration of the 48-hour diplomatic window regarding the Strait of Hormuz. Following U.S. President Donald Trump’s “extremely hard” rhetoric on Friday, the IRGC has officially implemented a “Security Toll” on all vessels, effectively seizing control of 20% of global oil flows. Consequently, Brent Crude has stabilized at $113.12/bbl, while the DXY (Dollar Index) has surged to 100.19, crushing emerging market currencies. Investors are pivoting aggressively into “Hard Assets” and Defense sectors as the theater of operations broadens across the Gulf.
The S&P 500 enters the April 6 session in a “Bearish Consolidation” phase, currently hovering near 6,382.40, reflecting a 9.5% drawdown from its Q1 peaks. Fundamentally, the index is being hollowed out by “Stagflationary Gravity,” where $110+ oil acts as a regressive tax on consumer spending while simultaneously forcing the Federal Reserve to maintain a “Hawkish Hold” despite slowing industrial production. Technically, the index has breached its 200-day moving average, a structural failure that has triggered systematic liquidation from algorithmic “Trend-Following” funds. The CBOE VIX stands at 31.05, its highest sustained level since 2022, indicating that institutional hedging is no longer elective but mandatory for portfolio survival. Resistance is firmly established at 6,600, a level that has rejected three separate relief rallies over the past fortnight, while the primary support floor is now identified at 6,250. Defense contractors like Lockheed Martin and Northrop Grumman are the only components showing a positive “Beta,” decoupling from the broader market slide as the U.S. surges munitions to the Gulf. Fundamental analysis suggests that if the Hormuz blockade persists past mid-April, S&P 500 earnings estimates for 2026 will be revised downward by an additional 7%. Traders are currently maintaining high cash ratios, awaiting Fed Chair Powell’s scheduled remarks tonight for any hint of a “Geopolitical Pivot” in monetary policy. Sentiment is “Strong Bearish,” with a “Sell on Strength” bias dominating the NY session.
The Nikkei 225 has retreated into a “Defensive Crouch,” closing the Monday session at 53,476.06 (-3.97%) as the Japanese market digests its 90% dependency on Middle Eastern crude. Fundamentally, the index is the global “Epicenter of Energy Fragility,” where every $10 increase in Brent equates to a 1.2% drag on Japan’s GDP, forcing the BoJ into a policy deadlock. Technically, the index has opened a massive “Bearish Gap” at 54,500, with price action now testing the critical horizontal support at 52,800, which represents the 2025 breakout base. The USD/JPY at 160.25 has triggered acute intervention anxiety, as the inflationary “Import Tax” of expensive energy now entirely erases the traditional export benefits of a weak Yen. Fundamental analysis suggests that Japanese electronics and automotive giants are facing an existential margin crisis, with supply chains for rare gases paralyzed by the maritime blockade. Sentiment is “Extreme Fear,” as the Tokyo floor braces for potential industrial energy rationing if the “Toll Law” in Hormuz is not revoked by the G7. Institutional players are rotating out of growth tech and into the “Sogo Shosha” (trading houses), which stand to benefit from commodity arbitrage in a fractured global trade environment. A breach below 52,000 would likely signal a structural collapse toward the 48,000 psychological floor.
The Saudi Tadawul (TASI) continues to function as the global “Antifragility Hedge,” trading near 11,090.33 (+0.09%) as it benefits from the $110+ oil floor. Fundamentally, the index is decoupled from the growth scares of the West, as record energy revenues ensure the continuation of “Vision 2030” infrastructure projects despite the regional conflict. Technically, the TASI is one of the few global indices in a clean “Bullish Trend,” with its 50-day moving average providing a rock-solid support at 10,830 on every minor dip. Resistance is projected at the multi-year high of 11,350, a level that institutional desks expect to see breached if Saudi Arabia further increases production to offset the “obliterated” Iranian capacity. However, the UAE’s ADX General (-0.06%) reflects minor retail jitters following drone interceptions over the weekend near Abu Dhabi industrial zones. Fundamental analysis suggests that the regional banking sector remains stable, though the “Tail Risk” of direct strikes on desalination plants keeps insurance premiums for local assets at record highs. Sentiment is “Neutral-Bullish,” contingent on the permanence of the U.S. naval escort program and the stability of local air defenses against IRGC drone swarms.
Germany’s DAX 40 is currently the “Sick Man of Global Equities,” trading near 22,330 as the Eurozone faces a historic energy-driven re-rating. Fundamentally, the index is being crushed by the effective blockade of Qatari LNG exports, which has sent EU natural gas benchmarks up by 128% month-to-date, crippling the chemical and steel sectors. Technically, the DAX is tracing a “Bearish Flag” on the daily chart, with immediate support at 22,100 and a resistance ceiling now stationed at a formidable 22,900. The European Central Bank is in a “Policy Trap,” unable to signal rate cuts to save the manufacturing sector because of “imported inflation” from the $113 Brent price de-anchoring the Euro. Traders are prioritizing defensive healthcare and utilities (RWE/E.ON) as a survival strategy, while high-beta automotive giants like Volkswagen trade at multi-year lows on supply chain paralysis. Fundamental de-rating of the industrial core is accelerating, with BASF and ThyssenKrupp reporting a 30% surge in energy-input costs per unit. Resistance at 23,100 remains an impenetrable barrier until a naval corridor is physically secured and energy transit resumes. Sentiment is “Extreme Fear,” as the region braces for the potential of mandatory industrial energy rationing starting in May 2026.
| Instrument | Live Price/Rate | Day Change % | Support | Resistance | Tech/Fund Analysis |
| USD/INR | ₹95.23 | +0.44% | 94.50 | 96.00 | Record Low. Capital flight to USD safety. |
| DXY Index | 100.19 | +0.09% | 99.80 | 100.50 | Safe-Haven. Pivot for hawkish Fed tone. |
| Bitcoin (BTC) | $65,540 | -0.68% | $64,000 | $68,600 | Risk-Off. Acting as high-beta proxy. |
| Brent Crude | $113.12 | +0.48% | $105.00 | $120.00 | War Premium. 95% traffic drop in Hormuz. |
| WTI Crude | $99.84 | +0.20% | $92.00 | $105.00 | Supply Panic. SPR releases under focus. |
| Commodity | Live Price | Day Change % | Support | Resistance | Technical Detail |
| Gold (XAU) | $4,510.50 | +0.35% | $4,400 | $4,650 | Ultimate Hedge. 45% YoY surge on war. |
| Silver (XAG) | $69.80 | +0.30% | $65.00 | $75.00 | Dual Bid. Industrial safety hybrid bid. |
| Steel (Fe) | $1,065.00 | +0.28% | $950 | $1,100 | 26-Month High. Logistics paralysis. |
| Iron Ore | $106.35 | +0.12% | $100.00 | $112.00 | China Floor. High India imports (+2x). |
The Indian market witnessed a “Monday Meltdown” as it digested the Good Friday job data and the expiration of the Gulf diplomatic window.
| Index | Close (April 6) | Change (Pts) | Change (%) | Summary |
| Nifty 50 | 22,331.40 | -488.20 | -2.14% | Slipped below 22,500 base; Bearish Marubozu. |
| Sensex | 71,947.55 | -1,635.67 | -2.22% | Wealth erosion of ₹10 lakh crore. |
| Bank Nifty | 50,850.20 | -1,250.40 | -2.40% | Crushed by RBI FX restrictions & FII exit. |
| India VIX | 28.00 | +2.16 | +8.80% | Extreme Fear. VIX tops 28. |
The user requested the March 20 baseline for comparison against the current April 6 meltdown.
| Date | FII Cash (₹ Cr) | DII Cash (₹ Cr) | Net (₹ Cr) | Sentiment |
| March 20 (Baseline) | -5,518.40 | +5,706.20 | +187.80 | Balanced Absorption |
| April 6 (Live Prov.) | -11,489.30 | +8,338.71 | -3,150.59 | Systemic Liquidation |
| Top 5 Gainers | % Change | Sector | Top 5 Losers | % Change | Sector |
| ONGC | +2.12% | Energy | Bajaj Finance | -5.01% | NBFC |
| Coal India | +1.88% | Energy | SBI | -3.93% | PSU Bank |
| Power Grid | +0.21% | Utility | IndiGo | -3.81% | Aviation |
| Tech Mahindra | +0.18% | IT | Axis Bank | -3.65% | Bank |
| Reliance | +0.15% | Energy | Kotak Bank | -3.49% | Bank |
| Time (IST) | Country | Event / Data Release | Forecast | Previous | Impact |
| 11:30 AM | India | Fiscal Deficit (Full Year) | 14.2T | 15.1T | Medium |
| 05:12 PM | India | Index of Industrial Production | 4.8% | 5.2% | Medium |
| 07:00 PM | US | Fed Chair Powell Speaks | — | — | CRITICAL |
| 10:30 PM | US | 3-Month & 6-Month Bill Auctions | — | 3.63% | Medium |
The market behavior for the rest of April 6 is defined by “Cash Preservation.” With the Nifty below 22,500 and the Rupee at 95.23, the structural bias remains “Sell on Rise.”
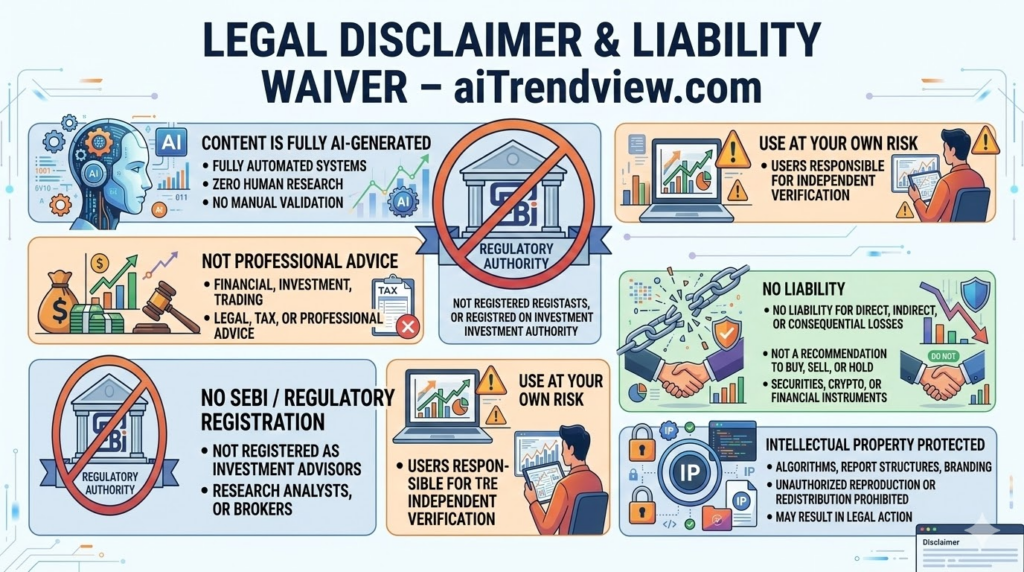
All content, reports, signals, analytics, forecasts, and materials published on aiTrendview.com are fully AI-generated outputs produced through automated systems with zero human research, manual validation, editorial review, or professional intervention. This platform does not provide financial, investment, trading, legal, tax, or professional advice of any kind. aiTrendview.com, its owners, affiliates, and associated entities are not registered with SEBI or any other regulatory authority as investment advisors, research analysts, brokers, or financial consultants. All data is autonomously aggregated from publicly available sources and algorithmic processes that may contain inaccuracies, delays, omissions, or technical errors. Users are solely and exclusively responsible for independently verifying all information before making any financial, legal, or commercial decisions. By accessing or using this platform, you expressly acknowledge and agree that any reliance on the information provided is entirely at your own risk. aiTrendview.com assumes absolutely no liability for any direct, indirect, incidental, consequential, financial, legal, trading, or other losses arising from the use of, reliance upon, or inability to use any content or data published. Nothing on this platform shall be construed as a solicitation, endorsement, or recommendation to buy, sell, hold, or speculate in any security, derivative, commodity, cryptocurrency, or financial instrument. All intellectual property, including but not limited to algorithms, report structures, proprietary formats, branding, and system outputs, is strictly protected under applicable intellectual property laws. Unauthorized reproduction, redistribution, modification, or commercial exploitation is strictly prohibited and may result in civil and criminal legal action.


