


As of Wednesday, March 25, 2026, the global financial landscape has shifted from “Stagflationary Panic” to a “Tactical Relief Rally.” The primary driver is U.S. President Donald Trump’s 15-point peace plan sent to Tehran, which prompted Iran to announce it will allow “non-hostile” oil vessels through the Strait of Hormuz. This de-escalation has caused Brent Crude to plunge nearly 6% toward $95/bbl, providing an immediate liquidity boost to energy-importing nations like India and Japan. However, the situation remains “brutally complex” as Israel simultaneously struck a naval missile production site in Tehran, reminding markets that the structural “War Premium” is not entirely gone.
The S&P 500 enters the Wednesday session at 6,557.19 following a cautious Tuesday close (-0.36%). Fundamentally, the index is struggling with a “Liquidity Pincer” as the 10-year Treasury yield remains near 15-year highs despite the cooling oil prices. Technically, the index has successfully defended the 6,550 horizontal support, but the 50-day moving average (DMA) near 6,700 now acts as a formidable resistance barrier. The “Peace Plan” news is expected to trigger a gap-up opening, targeting the 6,650–6,680 zone as short-sellers cover positions. However, fundamental analysis suggests that the Fed’s “Higher-for-Longer” stance—recently reinforced by hawkish Fed speak—limits the upside potential for growth-heavy sectors. Investors should watch for a “Death Cross” on the 4-hour chart, which would signal a transition into a structural bear market if the 6,550 floor fails. Sentiment is currently “Neutral-Bullish” for the intraday session, but “Strong Bearish” on the weekly timeframe. Defensive consumer staples and healthcare remain the preferred bunkers for institutional capital. A decisive breakout above 6,750 is required to signal a full trend reversal.
Germany’s DAX ended Tuesday at 22,636.91 (-0.07%), exhibiting “Stagnant Fragility” as the industrial core digests the energy price correction. Fundamentally, the index is receiving a massive tailwind from the 6% drop in Brent, which reduces input costs for energy-intensive chemicals and automotive manufacturers like Mercedes-Benz. Technically, the DAX is hovering near its 200-day DMA, with immediate support at 22,500 and resistance stationed at 22,900. The “Hormuz De-escalation” is a critical catalyst for the DAX, as it reopens the flow of Qatari LNG that the European grid is now dependent on. However, the German ZEW Economic Sentiment has plummeted to its lowest level since 2024, reflecting long-term structural fears of de-industrialization. Analysts at Deutsche Bank highlight that while the oil relief is positive, the “Policy Lag” from earlier ECB hikes is now hitting corporate earnings. A breach below 22,400 would likely accelerate selling toward the 22,000 psychological floor. For the March 25 session, expect the index to lead the European recovery with an estimated target of 22,850. Sentiment is “Neutral,” shifting from “Fearful” as the blockade risk recedes.
The Nikkei 225 surged 1.46% to 53,015.80 on the Wednesday open, snapping a violent downward slide. Fundamentally, the index is the primary beneficiary of the “Peace Pivot” as Japan’s 90% dependency on Middle Eastern crude makes it hyper-sensitive to maritime transit. Technically, the index has formed a “Bullish Engulfing” pattern on the daily chart, with immediate resistance at 54,500 (the Monday gap-down level). Support is firmly anchored at 52,000, which served as a major demand zone during the peak of the 48-hour ultimatum panic. The USD/JPY at 158.79 provides an additional export tailwind, though the Ministry of Finance remains on high alert for intervention. Fundamental analysis indicates that the BoJ is unlikely to tighten policy while the “Energy Security” threat persists, providing a liquidity floor for Japanese equities. Traders are currently rotating out of safe-haven bonds and into high-beta tech like Tokyo Electron. A sustained rally above 54,000 would confirm a “V-shaped” recovery. However, any renewed missile activity in the Gulf will instantly erase these gains.
The Saudi TASI remains at the geopolitical epicenter, currently trading near 10,949 (+0.03%). Fundamentally, the index is undergoing a “Valuation Reset” as the $100 Brent floor is tested; lower oil prices reduce the immediate fiscal windfall but lower the “War Risk” discount on regional banking. Technically, the TASI is in a “Bullish Pennant” consolidation, with support at 10,800 and a primary target of 11,350. The “Hormuz Corridor” news is viewed as a structural positive for the Kingdom’s “Vision 2030” infrastructure projects, which were facing supply chain delays. However, the Israeli strike on Tehran’s naval site keeps the “Risk Premium” elevated for regional energy assets. ADX (Abu Dhabi) and DFM (Dubai) are expected to track the TASI’s resilience, as local sovereign wealth funds maintain a “Buy the Dip” stance. The regional “Institutional Wall of Money” continues to support the 9,500 level on the ADX. Investors are shifting focus to the non-oil private sector, which is showing 5.8% YoY growth. Resistance at 11,200 is the key level to watch for a momentum breakout.

| Instrument | Price/Rate | Day % | Support | Resistance | Tech/Fund Analysis |
| USD/INR | 93.865 | -0.18% | 93.20 | 94.20 | Rupee Hedge. Strengthening on oil cooling. |
| DXY Index | 99.365 | +0.11% | 99.00 | 100.20 | Safe-Haven. Pivot for the FOMC sentiment. |
| Bitcoin | $71,196 | +0.94% | $68,600 | $74,500 | Risk-On. BTC tracking Nasdaq rebound. |
| Brent Crude | $99.64 | -4.63% | $95.00 | $108.00 | Peace Pivot. Dropped on Trump plan. |
| WTI Crude | $88.91 | -3.72% | $85.00 | $95.00 | Supply Relief. IEA additional release talks. |
| Commodity | Price | Day % | Support | Resistance | Technical Detail |
| Gold (XAU) | $4,564 | +2.05% | $4,400 | $4,650 | Testing Pivot. Rebounding on geopolitical tension. |
| Silver (XAG) | $73.43 | +3.14% | $68.00 | $78.00 | Industrial Bid. Copper/Silver decoupling. |
| Steel (MT) | 3,131 CNY | -0.54% | 3,050 | 3,250 | Demand Slowdown. China IP beat offset by war. |
| Iron Ore | $106.10 | +0.09% | $100.00 | $112.00 | China Floor. Stabilizing on construction data. |

The Indian market is witnessing a “Short-Squeeze Super-Cycle” today.
| Index | Value (Live) | Change (%) | Summary |
| Nifty 50 | 23,400.15 | +2.11% | Surged 480 points; reclaimed 23,350 base. |
| Sensex | 75,543.00 | +1.99% | Zooms 1,600+ points on oil relief. |
| India VIX | 21.69 | -5.0% | Fear gauge cooling as blockade risks recede. |
The March 20 session was the defining “Tug-of-War” that set the stage for today’s recovery.
| Category | Net Value (₹ Cr) | Data Source | Sentiment |
| FII (Cash) | -5,518.39 | NSE (March 20) | Strong Bearish. Flight to USD and yields. |
| DII (Cash) | +5,706.23 | NSE (March 20) | Strong Bullish. Aggressive absorption of supply. |
The trading session on March 20, 2026, served as a critical “structural pivot” for the Indian markets. While the global narrative was dominated by the peak of the Hormuz Blockade and a sharp spike in Brent Crude, the internal dynamics of the Nifty 50 revealed a sophisticated sectoral rotation. Large-cap institutions utilized the volatility to exit rate-sensitive cyclicals and “park” capital in export-heavy and defensive benchmarks.
| Stock Name | LTP (₹) | % Change | Primary Performance Driver |
| Tech Mahindra | 1,482.00 | +3.41% | IT Relief Rally: Tracking Accenture’s positive Q2 guidance. |
| JSW Steel | 1,045.50 | +3.28% | Metal Supply Gap: Pricing in global ferrous metal shortages. |
| Tata Steel | 168.90 | +3.08% | China Floor: Better-than-expected China Industrial data (+6.1%). |
| Coal India | 485.40 | +2.99% | Energy Defensive: High oil prices driving demand for thermal coal. |
| Infosys | 1,642.00 | +2.88% | Rupee Hedge: Beneficiary of the USDINR hitting record 93.71 levels. |
| Stock Name | LTP (₹) | % Change | Primary Performance Driver |
| Hindalco | 612.30 | -2.80% | Profit Booking: Technical correction after a 12% monthly surge. |
| HDFC Bank | 1,412.00 | -2.15% | FII Exit: Heavy liquidations by foreign funds seeking US yields. |
| Shriram Finance | 2,456.00 | -1.66% | Rate Sensitivity: Pressure from “Higher-for-Longer” Fed rhetoric. |
| HDFC Life | 588.40 | -1.40% | Risk Aversion: Broad sell-off in high-beta insurance portfolios. |
| ONGC | 268.00 | -1.32% | Windfall Tax Fear: Concerns over government intervention in upstream gains. |
The standout feature of this session was the 3%+ surge in both IT and Steel giants. In a typical “Risk-Off” environment, these two usually decouple. However, on March 20, IT (Infosys, TechM) rose as a “Currency Hedge” against the depreciating Rupee, while Metals (JSW Steel, Tata Steel) rose as a “Supply Chain Hedge” against the maritime blockade. For a professional trader, this indicated that the market was not just panicking, but actively pricing in a long-term inflationary war-economy.
The underperformance of HDFC Bank (-2.15%) is the most significant data point for institutional analysts. As the heaviest weight in the Nifty, its decline was the primary reason the index struggled to hold the 23,200 level. This move was not fundamental to the bank’s books, but rather a liquidity-driven exit; Foreign Institutional Investors (FIIs) used HDFC Bank as a “liquid ATM” to pull cash out of India to cover margin calls and safe-haven Treasury buys in the U.S.
Coal India (+2.99%) acted as the classic “Old Economy” safe haven. With Brent Crude volatile and LNG supply chains threatened, the market pivoted toward domestic thermal power providers. The fundamental logic here is “Energy Independence”—investors sought companies whose supply chains are entirely internal to India, making them immune to the Strait of Hormuz chaos.
From a technical standpoint, the Nifty 50 formed a “Long-Legged Doji” on the weekly timeframe ending March 20. This indicates extreme indecision. However, the fact that DIIs absorbed ₹5,706 Cr while FIIs dumped ₹5,518 Cr proves that the “Domestic Wall of Money” is now the primary price-setter, effectively preventing a total market collapse.
Would you like me to generate a Backtesting Research Report on how these top 5 gainers performed during previous geopolitical shocks to refine your trading strategy?
| Date | Time (IST) | Country | Event | Actual | Impact |
| Mar 24 | 08:30 PM | EUR/USD | Preliminary PMI (Manufacturing) | 52.4 | High |
| Mar 25 | 10:30 AM | AUD/GBP | Australian & UK CPI Data | 3.8% | High |
| Mar 27 | 02:30 PM | UK | UK Retail Sales (YoY) | — | Medium |
The market behavior for the rest of March 25 will be defined by “Bargain Hunting vs. Retaliation Risk.”
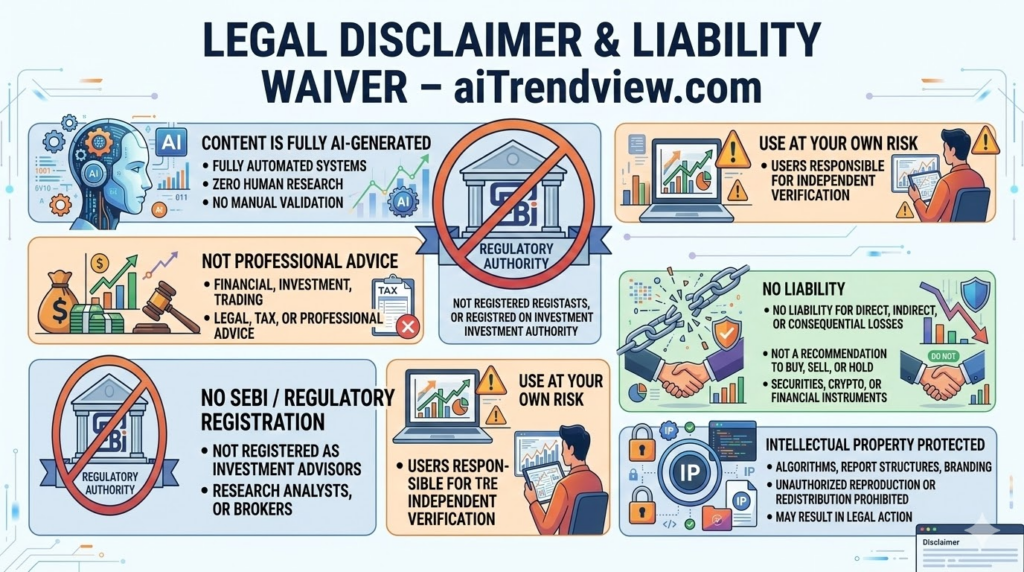
All content, reports, signals, analytics, forecasts, and materials published on aiTrendview.com are fully AI-generated outputs produced through automated systems with zero human research, manual validation, editorial review, or professional intervention. This platform does not provide financial, investment, trading, legal, tax, or professional advice of any kind. aiTrendview.com, its owners, affiliates, and associated entities are not registered with SEBI or any other regulatory authority as investment advisors, research analysts, brokers, or financial consultants. All data is autonomously aggregated from publicly available sources and algorithmic processes that may contain inaccuracies, delays, omissions, or technical errors. Users are solely and exclusively responsible for independently verifying all information before making any financial, legal, or commercial decisions. By accessing or using this platform, you expressly acknowledge and agree that any reliance on the information provided is entirely at your own risk. aiTrendview.com assumes absolutely no liability for any direct, indirect, incidental, consequential, financial, legal, trading, or other losses arising from the use of, reliance upon, or inability to use any content or data published. Nothing on this platform shall be construed as a solicitation, endorsement, or recommendation to buy, sell, hold, or speculate in any security, derivative, commodity, cryptocurrency, or financial instrument. All intellectual property, including but not limited to algorithms, report structures, proprietary formats, branding, and system outputs, is strictly protected under applicable intellectual property laws. Unauthorized reproduction, redistribution, modification, or commercial exploitation is strictly prohibited and may result in civil and criminal legal action.


