

Strategic Outlook: Geopolitical Friction vs. Industrial Resilience

As of Thursday, April 23, 2026, the global financial landscape is defined by an aggressive shift in maritime security and supply chain positioning. The primary catalyst is the worsening situation in the Strait of Hormuz, where Iranian forces have reportedly fired on and seized commercial vessels (including the MSC Francesca and Epaminondas). In a decisive counter-move, U.S. President Donald Trump has announced a total blockade of the Strait until Tehran agrees to terms, authorizing the sinking of any vessel laying mines. Consequently, Brent Crude has surged back above $106, while global equities have retreated into a defensive “Risk-Off” posture as the inflationary tax of higher energy costs begins to hit the manufacturing sector.
The U.S. markets concluded the Thursday session with a broad-based decline, as the S&P 500 slipped 0.42% to 7,108 and the Nasdaq Composite fell 0.89% to close at 24,439. Fundamentally, the market is navigating a “Stockpiling Paradox,” where the preliminary April manufacturing PMI reached a four-year high of 54.0, yet this strength is largely attributed to precautionary inventory building ahead of impending tariffs rather than organic demand. Technically, the S&P 500 is testing its 50-day moving average, with a critical “Line in the Sand” at 7,050, while the Nasdaq is grappling with a breakdown in the software segment following ServiceNow’s weak guidance. The fundamental outlook is clouded by the 10-year Treasury yield hitting 4.4%, effectively capping valuation multiples for high-growth tech components. Intel provided a rare bright spot, surging 20% in after-hours on strong Q2 guidance, but Tesla’s 3.56% drop underscored the inventory overhang in the EV sector. The VIX has spiked to 18.30, signaling a transition from complacency to active hedging as the Gulf blockade enters its most aggressive phase. Support for the Dow Jones is anchored at 44,500, while resistance for the Nasdaq remains formidable at 25,000. Institutional players are rotating into “Energy Independence” plays and defensive healthcare, reflecting a shift toward tangible cash flows. The interplay between record-high GPT-5.5 AI excitement and the physical reality of blocked oil channels is creating a highly fragmented market breadth.
Asian benchmarks displayed a sharp divergence on Thursday, with Japan’s Nikkei 225 gaining 0.58% to 59,485.30, while the Hang Seng plummeted 0.95% to 25,915.20. Fundamentally, the Nikkei is functioning as a “Safe-Haven Proxy” in Asia, supported by a resilient Yen and domestic industrial strength, even as the BoJ remains in a policy deadlock due to imported inflation. In contrast, the Hang Seng and Shanghai SSE are reeling from the secondary impacts of the Hormuz blockade, which has paralyzed critical electronics and rare-earth export routes. Technically, the Nikkei is facing horizontal resistance at 60,000, with a solid demand floor established at 58,000, while the Hang Seng has breached its 26,200 support, opening a path toward the 25,500 floor. The regional focus is on the PBoC’s recent decision to maintain rates, which has failed to provide a sufficient liquidity buffer against the global risk-off trend. Sentiment in the semiconductor-heavy indices remains fragile as Samsung and TSMC navigate shipping delays that are adding approximately 15% to logistics costs. Traders are currently “Sell on Rise” in the Hong Kong market, waiting for a definitive China fiscal package to offset the energy shock. Support for the KOSPI is stationed at 2,450, representing the multi-month breakout base. The Asian sector as a whole is pricing in a 12% increase in industrial input costs for the coming quarter if the naval standoff persists past April.
European indices showed relative resilience compared to the U.S., with the CAC 40 rising 0.87% to 8,227.32, while the DAX 40 dipped slightly by 0.16% to 24,155.45. Fundamentally, the Eurozone is the primary victim of the maritime blockade, with regional gas benchmarks surging as Qatari LNG tankers are diverted around the Cape of Good Hope. Technically, the DAX is tracing a “Bullish Pennant” on the daily chart, with a pivot point at 24,300 and a structural support floor at 23,850. The FTSE 100 was dragged down by a 0.13% decline to 10,449, weighed by a poor reception to Sainsbury’s results and general energy-linked inflation fears. Fundamental de-rating of the industrial core is being partially offset by strong defense spending, as European nations increase orders for munitions and naval hardware in response to the Gulf crisis. Resistance for the FTSE is capped at 10,600, while support is firmly anchored at the 10,250 mark where dip-buying has been consistent. European sentiment is “Cautiously Neutral,” as traders wait for Monday’s PPI data to confirm the peak of the industrial inflation cycle. The chemical and automotive giants in Germany are currently trading at a 15% discount to their five-year averages, reflecting the “War Discount” embedded in valuations.
Arab indices are currently navigating a “Revenue vs. Security” paradox, with the Dubai DFM edging up 0.27% to 3,360.39, while the Saudi TASI remains under pressure, down 13% YTD. Fundamentally, the region is benefiting from record-high oil realizations above $105, but the “Blockade Premium” on logistics and insurance is hollowing out the non-oil industrial sector. Technically, the DFM is attempting a breakout above the 3,400 hurdle, with a solid demand zone at 3,250, while the TASI is struggling near the 10,490 psychological support. Fundamental analysis suggests that the GCC banking sector is showing robust credit growth, but international institutional funds are maintaining a defensive underweight stance due to the proximity of the conflict. The UAE’s ADX has gained roughly 6% since the start of the year, outperforming its regional peers on the back of resilient real estate demand. Sentiment is “Neutral-Negative” for the broader region as Tehran continues to exert physical control over the waterway, restricted nearly all international traffic. Traders are watching for a “Peace Proposal” from Iran as the current truce remains place indefinitely, according to President Trump. Resistance for the TASI is projected at 11,000, with any failure to hold 10,200 signaling a deeper structural correction.

| Instrument | Live Price | Trend | Support | Resistance | Tech/Fund Analysis |
| USD/INR | ₹94.28 | Bullish | 93.80 | 94.50 | Record Low. Pressure from $105 Brent. |
| DXY Index | 104.20 | Bullish | 103.50 | 105.00 | Safe-Haven. Pivot for hawkish Fed tone. |
| Bitcoin (BTC) | $78,200 | Bullish | $75,000 | $82,000 | Consolidating. Targets $85k on risk-off. |
| Brent Crude | $106.02 | Parabolic | $100.00 | $112.00 | War Premium. US blockade impact. |
| WTI Crude | $96.58 | Bullish | $92.00 | $105.00 | Supply Panic. Volatile vertical surge. |
| Gold (Spot) | $4,717 | Bearish | $4,650 | $4,820 | Profit-booking. Strong DXY trap. |
| Steel (HRC) | $3,133 | Bullish | $3,050 | $3,250 | Supply Gap. Logistics paralysis. |
| Iron Ore | $106.55 | Stable | $100.00 | $112.00 | China Floor. Steady infra demand. |

The Indian market suffered a “Black Thursday” scenario, erasing the relief of the prior session as benchmark indices buckled under the weight of $106 Brent.
| Metric | Value (Live) | Change (%) | Technical Status |
| Nifty 50 | 24,173.05 | -0.84% | Slipped below 24,200; testing 24k support. |
| BSE Sensex | 77,664.00 | -1.09% | Tanked 852 points; resistance at 79k. |
| Bank Nifty | 56,305.00 | -1.43% | Resistance near 200-DMA (57,800). |
| India VIX | 18.30 | +4.40% | Fear gauge rising as geopolitical risk spikes. |
The March 20 baseline shows the peak panic of the initial war phase, while April 23 reflects the “Decoupling” phase where domestic capital buffers the FII exit.
| Category | March 20 (Baseline) | April 23 (Live) | Segment Trend |
| FII (Net) | -₹5,518.40 Crore | -₹3,254.71 Crore | Continuous Exit. Decelerating vs. March. |
| DII (Net) | +₹5,706.20 Crore | +₹941.35 Crore | Structural Support. Absorbing the sell-off. |
| TOTAL (MoM) | -₹1,22,540 Cr (FII) | +₹1,42,960 Cr (DII) | Domination Shift. DIIs now control the floor. |
| Top 5 Gainers | % Change | Sector | Top 5 Losers | % Change | Sector |
| Dr. Reddy’s | +8.87% | Pharma | Trent | -4.30% | Retail |
| Cipla | +6.02% | Pharma | Shriram Fin | -3.32% | NBFC |
| Jio Financial | +4.00% | Fin. | Tech Mahindra | -3.31% | IT |
| Sun Pharma | +2.20% | Pharma | HDFC Bank | -1.82% | Bank |
| Reliance | +1.61% | Energy | Infosys | -1.50% | IT |
Today’s trading floor is a battlefield between the “Digital Alpha” of GPT-5.5 and the “Physical Friction” of the Strait of Hormuz. For the Indian investor, the 852-point Sensex crash is a “Blockade Tax”—the price we pay for being a net energy importer in a world where the US and Iran are in a physical stalemate.
While FIIs have dumped over ₹1.2 lakh crore this year, the “Genius” move is to recognize that we are no longer in a single-engine market. The ₹1.4 lakh crore DII inflow in March is the most significant structural shift in the history of Indian equities. We are witnessing the birth of a “Twin-Engine” market where domestic capital defines the floor, not foreign sentiment.
The Professional Outlook: Stay defensive. The Pharma rally (+2%) is a flight to safety. Avoid high-beta retail (Trent -4.3%) and IT as the ₹94.28 Rupee creates currency depreciation losses for FIIs, fueling further algorithmic selling. Your “Safe Harbor” remains the 24,100 Nifty floor; as long as we hold that, the structural uptrend is wounded but not dead.
Technical Alert: Watch the 24,500 Call Strike. Massive writing here indicates it will act as the “Great Wall” for the April series.
Legal Disclaimer & Liability Waiver – aiTrendview.com
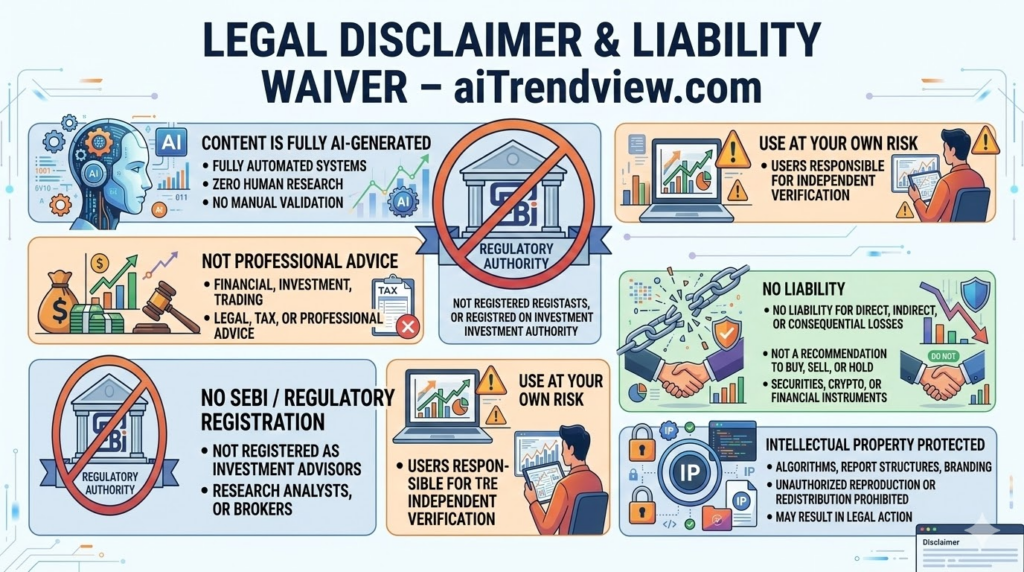
All content, reports, signals, analytics, forecasts, and materials published on aiTrendview.com are fully AI-generated outputs produced through automated systems with zero human research, manual validation, editorial review, or professional intervention. This platform does not provide financial, investment, trading, legal, tax, or professional advice of any kind. aiTrendview.com, its owners, affiliates, and associated entities are not registered with SEBI or any other regulatory authority as investment advisors, research analysts, brokers, or financial consultants. All data is autonomously aggregated from publicly available sources and algorithmic processes that may contain inaccuracies, delays, omissions, or technical errors. Users are solely and exclusively responsible for independently verifying all information before making any financial, legal, or commercial decisions. By accessing or using this platform, you expressly acknowledge and agree that any reliance on the information provided is entirely at your own risk. aiTrendview.com assumes absolutely no liability for any direct, indirect, incidental, consequential, financial, legal, trading, or other losses arising from the use of, reliance upon, or inability to use any content or data published. Nothing on this platform shall be construed as a solicitation, endorsement, or recommendation to buy, sell, hold, or speculate in any security, derivative, commodity, cryptocurrency, or financial instrument. All intellectual property, including but not limited to algorithms, report structures, proprietary formats, branding, and system outputs, is strictly protected under applicable intellectual property laws. Unauthorized reproduction, redistribution, modification, or commercial exploitation is strictly prohibited and may result in civil and criminal legal action.


