

Date: Wednesday, April 15, 2026 | Sentiment: Cautious Optimism / Geopolitical De-risking

As of Wednesday, April 15, 2026, global financial markets are undergoing a significant structural “relief rally.” The defining catalyst is the announcement from U.S. President Donald Trump late Tuesday that a second round of peace talks with Tehran could materialize within the next 48 hours. This diplomatic signal has effectively broken a six-week losing streak for global equities. Brent Crude has retreated below $95/bbl, providing a massive liquidity buffer to energy-importing nations. While the Strait of Hormuz remains technically under a naval blockade, reports that Iran is considering a “temporary suspension of transit fees” to facilitate negotiations have fueled a global short-squeeze across technology and industrial sectors.
The S&P 500 enters the Wednesday session at 6,967.38, surging 1.2% to sit just 0.2% below its all-time January record. Fundamentally, the index is powered by a “Binary Pivot”: the removal of the catastrophic $120 oil scenario combined with a stellar 12% YoY growth forecast for Q1 corporate earnings. Technically, the index has cleared its 50-day moving average and is now hammering against the psychological 7,000 resistance wall, with immediate support anchored at 6,755. The MACD histogram remains bullish, signaling consistent momentum, while the RSI is approaching 70, indicating a potential for a short-term corrective pause before a fresh breakout. Fundamental analysis reveals that financial and software companies are leading the charge, as cooling yields (10Y below 4.3%) reduce the discount rate on future cash flows. The “Fear and Greed Index” has improved to 47 (Neutral) from last month’s panic level of 21, reflecting a stabilization in institutional sentiment. However, the index remains “hostage to headlines,” where any failure in the Friday Islamabad-follow-up talks could trigger a 200-point liquidation. Large-cap tech components like Nvidia (+2.8%) and Amazon (+4.1%) are acting as the market’s “High-Beta” engine. Traders are advised to monitor the 6,800 level as a trailing stop for the current relief rally. The sentiment is “Neutral-Bullish,” contingent on the avoidance of a secondary escalatory spiral in the Gulf.
Japan’s Nikkei 225 closed Wednesday at 58,122.52 (+0.4%), successfully reclaiming its rising trend channel in the medium-to-long term. Fundamentally, the index is the primary beneficiary of the “Energy Windfall,” as Japan’s extreme dependency on Gulf crude makes every $5 drop in Brent a direct boost to manufacturing margins. Technically, the index has broken its immediate resistance and is now eyeing the 58,800 structural peak, with a rock-solid demand floor established at 56,500. The USD/JPY near 159.00 remains a dual-edged sword: aiding export realization for automotive giants like Toyota but keeping the BoJ in a “hawkish hold” stance due to import inflation. Fundamental data showing a 1.3% GDP revision and the first real wage increase in months provides a sturdy valuation floor for domestic equities. Sentiment is “Strong Bullish,” as traders rotate back into electronics and machinery sectors that were previously paralyzed by logistics risks. A sustained breakout above 59,000 would confirm a V-shaped recovery from the March blockade lows. Analysts warn that the “Hormuz Premium” still adds roughly ¥4,000 of risk-weighting to the index’s fair value.
The German DAX remains the global “Epicenter of Fragility,” trading flat near 23,000 as it balances earnings resilience against a deteriorating macro backdrop. Fundamentally, the index is supported by “Cost Discipline” among industrial champions like Siemens and BASF, who have managed to protect margins despite a 135% surge in EU gas benchmarks earlier this year. Technically, the DAX is tracing a “Bearish Flag” on the weekly chart, with resistance stationed at 23,400 and a critical liquidity floor at 22,500. The ECB’s potential pause in rate hikes—driven by a “wait-and-see” approach to the peace talks—has provided a temporary relief bid for rate-sensitive utilities and real estate. However, the fundamental de-rating of the automotive sector continues to act as a gravitational pull, as global supply chain paralysis remains a persistent threat. Sentiment is “Neutral-Bearish,” as institutional funds prefer the relative safety of the FTSE 100’s commodity-heavy weighting over the DAX’s industrial sensitivity. A decisive close below 22,200 would likely signal a transition into a structural bear market for the Eurozone core. Analysts highlight that the “Policy Lag” from 2025 hikes is now hitting corporate earnings, making the index hyper-sensitive to any peace talk failure.
The Saudi Tadawul (TASI) closed at 11,486.18 (+0.52%), functioning as the global “Antifragility Play” in the current energy super-cycle. Fundamentally, the index is decoupled from Western growth fears, as $95+ oil ensures robust fiscal surpluses and high dividend visibility for heavyweights like Saudi Aramco. Technically, the TASI is attempting a breakout above its 11,500 resistance level, with primary support firmly anchored at the 10,700 mark which held during the March strikes. The regional sentiment is bolstered by the “Vision 2030” infrastructure projects, which remain on track despite the maritime blockade, buoying the domestic construction and banking sectors. However, the index’s performance is currently “hostage to de-escalation”: if a peace deal is signed, a sharp correction is expected as the “War Premium” exits oil prices. Sentiment is “Neutral-Contingent,” as local funds maintain a defensive stance while international capital uses the GCC as a geographic hedge against European stagflation. The UAE’s DFM (5,719.50) and ADX are following suit, supported by robust real estate demand and high bank margins. Resistance for the TASI is projected at 11,850 in a sustained oil-strength scenario.

| Sector | Instrument | Current Price (Live) | Day Change % | Support | Resistance | Tech/Fund Analysis |
| Forex | USD/INR | 93.4275 | -0.17% | 93.20 | 94.00 | Rupee Surge. Oil easing relief. |
| Forex | DXY Index | 100.12 | -0.45% | 99.80 | 101.50 | Safe-Haven Exit. Slipped to 6-week low. |
| Crypto | Bitcoin (BTC) | ₹74,06,597 | -0.56% | ₹68.5L | ₹75.0L | Risk-On Proxy. BTC tracking tech rally. |
| Energy | Brent Crude | $94.86 | -4.61% | $92.00 | $108.00 | Peace Pivot. Dropped on talk hopes. |
| Energy | WTI Crude | $90.70 | -0.51% | $88.00 | $96.00 | Supply Relief. SPR release rumors. |
| Precious | Gold (Spot) | $4,803.42 | -0.80% | $4,650 | $4,900 | Safe-Haven. Hovering near $4.8k highs. |
| Precious | Silver | $78.69 | -0.99% | $75.00 | $82.00 | Industrial Bid. Strong 2026 performance. |
| Ferrous | Steel (HRC) | $3,086.00 | +0.13% | $2,950 | $3,250 | Logistics Risk. Choked supply chain. |
| Ferrous | Iron Ore | $106.35 | +0.12% | $100.00 | $112.00 | China Floor. Steady infrastructure demand. |
| Day | Country | Event / Indicator | Actual | Importance | Impact |
| Mon (13) | India | CPI Inflation (YoY) | 3.4% | High | Rupee stabilized. |
| Mon (13) | India | Coal Production | -4.09% | Medium | Supply bottleneck concerns. |
| Tue (14) | Germany | HICP (Inflation) | 2.7% | High | Pressure on ECB hikes. |
| Wed (15) | US | Empire State Mfg Index | -2.5 | Medium | Signaling industrial slowdown. |
| Thu (16) | Global | Trump-Iran Peace Talks | — | Critical | Potential Market Maker. |

The Indian market has staged a spectacular recovery today, reclaiming the psychological 24,200 level in a session that added ₹8.88 lakh crore to investor wealth.
| Metric | March 20 Baseline | April 15 Live Close | Change (%) | Technical Status |
| Nifty 50 | 23,114.50 | 24,231.30 | +4.83% | Golden Cross. Clearing all EMAs. |
| Sensex | 74,532.96 | 78,111.24 | +4.80% | Bullish Breakout. Targets 80k. |
| Nifty Bank | 53,856.10 | 55,912.75 | +3.82% | Rate-Sensitive Bid. Leading the recovery. |
| India VIX | 22.81 | 18.85 | -17.36% | Fear Evaporating. VIX below 20. |
The March 20 data reflects the peak “Panic Liquidation,” while April 13–15 shows the “Return of the Bull.”
| Rank | Top 5 Gainers | % Change | Top 5 Losers (March 20 Baseline) | % Change |
| 1 | IndiGo | +4.76% | Hindalco | -3.12% |
| 2 | Power Grid | +4.03% | Shriram Finance | -3.51% |
| 3 | Max Health | +4.03% | HDFC Bank | -1.82% |
| 4 | Wipro | +3.34% | SBI | -1.55% |
| 5 | NTPC | +2.91% | Titan Company | -1.22% |
Today is not a day for complacency; it is a day for “Tactical Re-entry.” The 1,200-point Sensex surge this morning is a classic reaction to the “Hormuz Relief” narrative. After 46 days of a grinding US-Iran war, the market is choosing to front-run the possibility of de-escalation rather than wait for the ink to dry.
For the Indian investor, the ₹456 lakh crore market cap milestone is a testament to the “Domestic Safety Net.” While FIIs sold over ₹1.2 lakh crore in March, the domestic SIP engine and now the “Peace Catalyst” have vindicated the “Buy the Dip” strategy.
The Genius Move: Focus on the Nifty Consumer Durables (+2.91%) and IT (+3.3%) sectors. If oil sustains below $95, these segments will see the fastest margin expansion. However, keep your stop-losses pinned at 23,800 Nifty, as the geopolitics of 2026 can turn on a single drone strike.
Behavioral Prediction: Expect a “Consolidation Day” for Thursday as traders de-risk ahead of the scheduled Trump-Iran talks on April 16.
Legal Disclaimer & Liability Waiver – aiTrendview.com
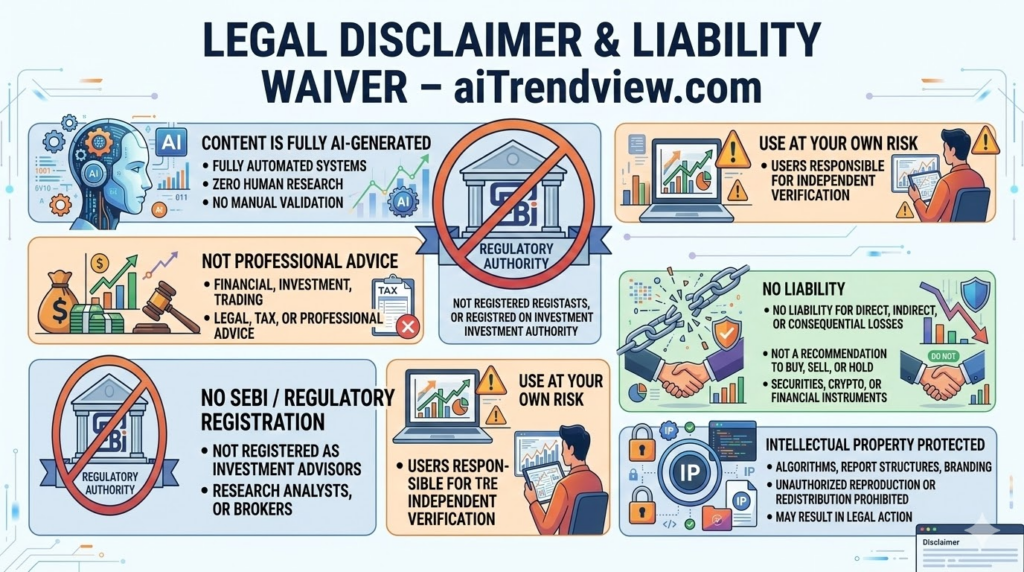
All content, reports, signals, analytics, forecasts, and materials published on aiTrendview.com are fully AI-generated outputs produced through automated systems with zero human research, manual validation, editorial review, or professional intervention. This platform does not provide financial, investment, trading, legal, tax, or professional advice of any kind. aiTrendview.com, its owners, affiliates, and associated entities are not registered with SEBI or any other regulatory authority as investment advisors, research analysts, brokers, or financial consultants. All data is autonomously aggregated from publicly available sources and algorithmic processes that may contain inaccuracies, delays, omissions, or technical errors. Users are solely and exclusively responsible for independently verifying all information before making any financial, legal, or commercial decisions. By accessing or using this platform, you expressly acknowledge and agree that any reliance on the information provided is entirely at your own risk. aiTrendview.com assumes absolutely no liability for any direct, indirect, incidental, consequential, financial, legal, trading, or other losses arising from the use of, reliance upon, or inability to use any content or data published. Nothing on this platform shall be construed as a solicitation, endorsement, or recommendation to buy, sell, hold, or speculate in any security, derivative, commodity, cryptocurrency, or financial instrument. All intellectual property, including but not limited to algorithms, report structures, proprietary formats, branding, and system outputs, is strictly protected under applicable intellectual property laws. Unauthorized reproduction, redistribution, modification, or commercial exploitation is strictly prohibited and may result in civil and criminal legal action.


