

Date: Friday, April 10, 2026 | Strategic Outlook: Tactical Euphoria / Geopolitical Fragility

As of Friday, April 10, 2026, the global financial architecture is suspended in a state of “Fragile Euphoria.” The headline of the day is the Islamabad Peace Summit, where a historic face-to-face between U.S. and Iranian delegations was scheduled. However, latest reports from Pakistan’s capital suggest a major deadlock: the Iranian team has refused to land in Islamabad until a definitive ceasefire is established in Lebanon, where Israeli strikes intensified overnight. Despite this “No Show” from Tehran, global equity markets—led by a late-night rally on Wall Street—are trading higher on the hope that Pakistani mediators can bridge the gap. Brent Crude remains the world’s most watched pulse, currently hovering between $95 and $99/bbl, as the Strait of Hormuz enters a “new phase” of Iranian management.
The S&P 500 entered the Friday session following a 0.62% gain in the previous night’s trade, currently positioning itself near the 6,680 mark as it digests the “Islamabad Impasse.” Fundamentally, the index is buoyed by the “run it hot” fiscal narrative of the Trump administration, which has prioritized domestic production and tax incentives despite the persistent war-inflation in energy costs. Technically, the index has successfully reclaimed its 50-day moving average, a move that has neutralized the immediate “Death Cross” fears that plagued the March series. Support is firmly anchored at the 6,350 liquidity floor, while the next major structural resistance is stationed at 6,750, a level where institutional supply has historically intensified during the Hormuz blockade. The VIX (Volatility Index) remains elevated above 20, signaling that while the bulls are back, the “tail risk” of a ceasefire collapse is still being priced into long-dated put options. Fundamental analysis suggests that 2026 earnings projections for the defense and energy sectors are being revised upward by 12% YoY, providing a sturdy value-floor for the broader index. However, the 10-year Treasury yield, hovering near multi-year highs, continues to exert a “valuation gravity” on high-beta growth tech, specifically in the semiconductor space. Sentiment is “Neutral-Bullish,” contingent entirely on the outcome of the Pakistani mediation efforts over the weekend. Traders are currently using a “Sell on Strength” strategy near 6,700 until the Strait of Hormuz reopening is physically verified by naval observers.
Japan’s Nikkei 225 has staged a violent recovery today, surging over 1% or 900 points to hit 56,815 on the Friday morning bell. Fundamentally, the index is the primary beneficiary of any de-escalation news in the Gulf, given Japan’s extreme 90% dependency on Middle Eastern crude; the cooling of Brent toward $95 is effectively an emergency tax cut for the Japanese industrial core. Technically, the index has cleared its 100-day EMA and is now testing the psychological resistance at 57,000, with support shifting upward to the 55,500 demand zone. The USD/JPY at 158.41 remains in a state of “Intervention Stasis,” as the BoJ maintains a cautious approach to rate hikes to avoid crashing the domestic credit markets during a global war shock. Export-heavy automotive giants like Toyota and machinery leaders are outperforming as the “Hormuz Risk Premium” begins to unwind, albeit slowly. Fundamental analysis indicates that Japan’s 2026 GDP revision (+1.3%) provides a structural floor, but the “Import Inflation” tax remains a long-term threat to consumer discretionary sectors. Sentiment is “Strong Bullish” for the intraday session, though volume profiles indicate that local retail investors are taking profit ahead of the Islamabad results. The “Hormuz Reset” narrative is driving capital back into Japanese trading houses (Sogo Shosha), which have built massive cash buffers through commodity arbitrage in Q1. Resistance at 58,500 remains the “Holy Grail” for the bulls to confirm a return to the 2025 super-cycle.
Europe’s DAX 40 is exhibiting “Fragile Resilience,” trading near 23,168 as it navigates the energy-driven stagflation that has defined the Eurozone since the February blockade. Fundamentally, the index is receiving a tactical tailwind from the better-than-expected China Industrial Production data, which supports Germany’s export-heavy machinery and luxury automotive sectors. Technically, the DAX is tracing a “Bearish Flag” on the daily chart, with a cluster of resistance at 23,400 capping any significant upside momentum for the current month. Support is firmly stationed at 22,500, a level that has provided a liquidity floor during three separate tests of the “Hormuz Crisis” throughout the first quarter. The ECB’s hawkish stance, necessitated by “imported inflation” from the elevated Brent price, continues to pressure valuations in rate-sensitive sectors like Real Estate. Sentiment is currently “Neutral-Bearish,” as the prospect of industrial energy rationing in a worst-case scenario continues to loom over European equities. Traders are prioritizing defensive healthcare and telecommunications over the high-beta industrial cycle as a “Survival Strategy” for Q2. A breach of the 22,000 psychological floor would confirm a shift from a correction into a formal structural bear market for the Eurozone core. Analysts at Deutsche Bank highlight that while the oil relief is positive, the “Policy Lag” from earlier ECB hikes is now hitting corporate earnings.
The Saudi Tadawul (TASI) continues its role as a “Structural Outperformer,” holding steady near 11,090 as the energy super-cycle provides a massive fiscal cushion for the Kingdom. Fundamentally, the index is decoupled from Western growth scares, as $95+ Brent ensures robust government spending and high dividend visibility for energy heavyweights like Aramco. Technically, the TASI is in a clean “Bullish Channel,” with its 50-day moving average providing a rock-solid support at 10,830 on every minor dip. Resistance is projected at the multi-year high of 11,350, a level that institutional desks expect to see breached if Saudi Arabia further increases production to offset the “new phase” of Iranian management. However, the UAE’s ADX General reflects minor retail jitters following weekend reports of expanded Israeli strikes in Lebanon, which Tehran has tied to the peace talks. Fundamental analysis suggests that the regional banking sector remains robust, with credit growth expected to hold at 10% for 2026 despite the surrounding conflict. Sentiment is “Strong Bullish” for energy and utility sectors, which are being accumulated by international funds seeking a “War Hedge” with high yield. Resistance at 11,500 is the key level to watch for a momentum breakout.
The FTSE 100 climbed 1.61% earlier in the week and continues to hover near the 10,436 mark, serving as a global inflation hedge due to its commodity weighting. Fundamentally, the index benefits from its high concentration of energy and mining giants (BP, Shell, Rio Tinto) that have harvested “War Windfalls” throughout Q1 2026. Technically, the index is navigating a complex resistance zone between 10,500 and 10,700, where profit-taking has historically intensified during de-escalation rumors. Support is firmly anchored at the 10,100 level, representing the 200-day SMA which has protected the index from a deeper “Stagflationary Slide.” The Bank of England’s “Higher for Longer” rhetoric continues to act as a headwind for the domestic mid-cap components (FTSE 250), which are more sensitive to consumer sentiment. Fundamental analysis shows that the UK’s 10-year yield is pricing in a “War Risk Premium” that the central bank is currently unable to mitigate without risking further Sterling weakness. Sentiment is “Neutral-Bullish,” supported by the high metal realization prices which have offset the recent dip in crude oil. The index is currently being used as a “Safe Haven” for European capital fleeing the industrial decay seen in Germany and France. Analysts warn that if the Islamabad talks fail, the FTSE will likely be the first to re-test its multi-year highs as oil resumes its climb toward $120.

| Instrument | Price (Live) | Day % | Support | Resistance | Tech/Fund Analysis |
| USD/INR | 92.62 | -0.12% | 92.10 | 93.40 | Rupee Resilience. Benefit from $95 Brent. |
| DXY Index | 99.42 | +0.05% | 98.80 | 100.50 | Safe-Haven Bid. Pre-Islamabad hedging. |
| Bitcoin (BTC) | $81,140 | +1.40% | $78,000 | $86,000 | Risk-On Proxy. BTC tracking Nasdaq rally. |
| Brent Crude | $96.12 | +2.18% | $92.00 | $100.00 | Fragile Floor. Iranian “new phase” in Hormuz. |
| Gold (MCX) | ₹1,52,540 | +0.30% | ₹1,45k | ₹1,58k | Ultimate Hedge. 45% YoY surge. |
| Silver (MCX) | ₹2,42,000 | +0.80% | ₹2,25k | ₹2,60k | Industrial Bid. Supply deficit in price discovery. |
| Steel (HRC) | $1,065.00 | +0.28% | $980 | $1,150 | Supply Deficit. Logistics paralysis at 26-mo high. |
| Time (IST) | Country | Event / Indicator | Forecast | Previous | Impact |
| 07:30 PM | US | Existing Home Sales (Mar) | 3.9M | 4.1M | Medium |
| 11:30 PM | US | Treasury Statement (Mar) | — | — | Medium |
| 05:30 AM | Canada | Building Permits (Feb) | +1.2% | -0.5% | Low |
| All Day | Global | IMF Spring Meetings Begin | — | — | High (Policy Shift) |

The Indian market has staged a spectacular “Gap-Up Friday,” reclaiming the psychological 24,000 mark in early trade as the “Islamabad Pivot” optimism offsets the local “Black Thursday” losses.
| Metric | Value (Live) | Change (%) | Technical Status |
| Nifty 50 | 23,978 | +0.85% | Testing 24,000 resistance hurdle. |
| Sensex | 77,261 | +0.82% | Surge of 630 points from early morning. |
| Bank Nifty | 55,420 | +1.10% | Reclaiming the 55k floor; supply at 55.8k. |
| India VIX | 20.69 | -3.71% | Cooling. Dropped after yesterday’s spike. |
| Top 5 Gainers | % Change | Sector | Top 5 Losers | % Change | Sector |
| Vedanta | +3.45% | Metal | Infosys | -1.15% | IT |
| SBI | +2.91% | Bank | Sun Pharma | -1.05% | Pharma |
| HDFC Bank | +2.68% | Bank | Tech Mahindra | -0.98% | IT |
| Tata Steel | +2.25% | Metal | HCL Tech | -0.85% | IT |
| Reliance | +2.14% | Energy | HUL | -0.65% | FMCG |
The user requested the March 20 baseline for comparison against the latest institutional behavior.
| Category | March 20 (Baseline) | April 9 (Yesterday) | 2026 Trend |
| FII (Cash) | ₹-5,518.40 Cr | ₹-1,711.00 Cr | Decelerating Sell. Liquidating less. |
| DII (Cash) | ₹+5,706.20 Cr | ₹+2,142.50 Cr | Strong Absorption. Domestic wall holding. |
| Net Institutional | +₹187.80 Cr | +₹431.50 Cr | Net Positive. Resilience is structural. |
Today, the world’s trading floors are holding their breath. The Islamabad Peace Pivot is no longer just a diplomatic headline; it is the sole anchor for the global market’s ₹200 lakh crore valuation. The deadlock in Pakistan—with Iran refusing to sit until Lebanon is quiet—has created a “Binary Market.”
For the Indian investor, the 630-point Sensex surge this morning is a “Leap of Faith.” While FIIs have slowed their selling to ₹1,711 Cr, the real story is the Metals and Banks (Vedanta/SBI) which are front-running a global industrial recovery.
The Genius Move: Do not chase the 24,000 Nifty breakout until the Islamabad talks move from “Deadlock” to “Delegation.” If the Iranian team doesn’t land by Saturday, Monday will see a “Gap-Down Massacre” as oil resumes its march toward $110. For now, enjoy the “Energy Dividend” in Autos and PSU Banks, but keep your stop-losses tight at 23,500.
Summary Performance: Global markets are “Pricing in Peace” but “Fearing the Fuse.” The Monday Outlook remains “High Volatility.”
Legal Disclaimer & Liability Waiver – aiTrendview.com
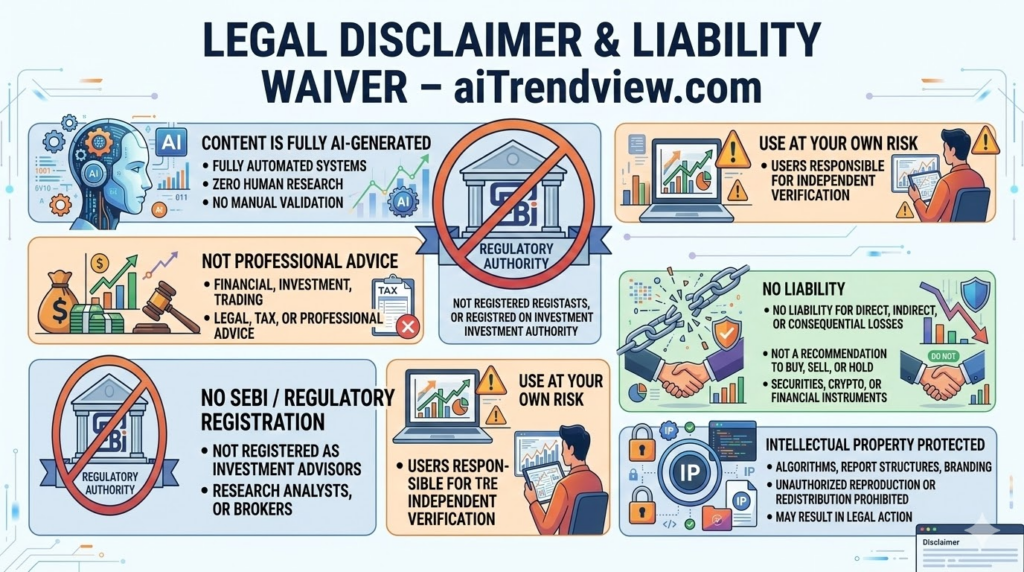
All content, reports, signals, analytics, forecasts, and materials published on aiTrendview.com are fully AI-generated outputs produced through automated systems with zero human research, manual validation, editorial review, or professional intervention. This platform does not provide financial, investment, trading, legal, tax, or professional advice of any kind. aiTrendview.com, its owners, affiliates, and associated entities are not registered with SEBI or any other regulatory authority as investment advisors, research analysts, brokers, or financial consultants. All data is autonomously aggregated from publicly available sources and algorithmic processes that may contain inaccuracies, delays, omissions, or technical errors. Users are solely and exclusively responsible for independently verifying all information before making any financial, legal, or commercial decisions. By accessing or using this platform, you expressly acknowledge and agree that any reliance on the information provided is entirely at your own risk. aiTrendview.com assumes absolutely no liability for any direct, indirect, incidental, consequential, financial, legal, trading, or other losses arising from the use of, reliance upon, or inability to use any content or data published. Nothing on this platform shall be construed as a solicitation, endorsement, or recommendation to buy, sell, hold, or speculate in any security, derivative, commodity, cryptocurrency, or financial instrument. All intellectual property, including but not limited to algorithms, report structures, proprietary formats, branding, and system outputs, is strictly protected under applicable intellectual property laws. Unauthorized reproduction, redistribution, modification, or commercial exploitation is strictly prohibited and may result in civil and criminal legal action.


